

Cash Advance - No credit Check
D.J. Advance App
- 4.7
- 2.82K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
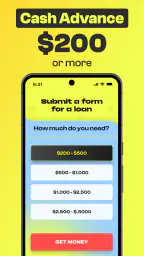
Cash Advance - No credit Check Pros and Cons
Pros
- Quick application process with minimal paperwork required.
- May help cover urgent expenses before your next payday.
- Clear repayment dates can make short-term planning easier.
- Available to users with limited or damaged credit histories.
- Mobile access lets you manage requests and repayments conveniently.
Cons
- Advance fees can make the total repayment more expensive than expected.
- Short repayment periods may be difficult for users on tight budgets.
- Approval and available amounts can vary by user and location.
- Late payments may lead to additional charges or collection activity.
- Not available in every state or country, limiting accessibility.
 Analysis by All-app
When an unexpected bill lands a few days before payday, the hardest part is often finding a clear way to understand your options quickly. Cash Advance - No credit Check is a free finance app from D.J. Advance App that presents itself as a way to explore cash-advance and loan possibilities without making a traditional credit check the center of the experience. I approached it as a practical tool for short-term money questions rather than as a replacement for a bank account, emergency fund, or carefully compared loan product.
My overall impression is mixed in a useful way. The app can be convenient for someone who wants to investigate short-term borrowing from a phone, especially when a conventional lender may not be a realistic first stop. At the same time, the phrase “no credit check” should not be treated as a promise of approval, low cost, or instant access to money. The important work still happens when you read the terms, check the total repayment, and decide whether borrowing is sensible at all.
How the app feels in its current form
The app sits in the finance category and is free to install, which makes it easy to try without paying an upfront fee for the app itself. It is intended for Everyone, and it supports Android devices running version 7.0 or later. That broad compatibility is useful if you are using an older phone, although the age of a device can still affect how comfortable any finance workflow feels.
Its current version is 1.1.3, while the app was released on December 5, 2022. I see that combination as a sign that the product has had time to establish a basic identity, but it is still important to judge the present experience rather than assume that a financial app has the depth of a long-established banking platform. The developer is D.J. Advance App, and the product has attracted a 4.7 average from around 34 thousand ratings, with roughly 2.8 thousand written reviews. It has also passed half a million installs, so this is not an obscure experiment that only a handful of people have encountered.
The strongest part of the concept is its focus. Instead of asking me to manage spending, track investments, or build a full personal-finance dashboard, it addresses a narrower question: what can I do if I need short-term cash before my regular income arrives? That makes the app easier to understand than a broad finance suite. The trade-off is that a narrow borrowing tool cannot replace the planning and comparison features I would want for long-term financial decisions.
I would also separate the app from the actual lending decision. An app can help connect a user with an offer or explain a possible route, but that does not mean every person will receive the same result. Eligibility, repayment conditions, timing, and cost can vary according to the provider behind an offer and the user’s circumstances. I would never install it expecting that the words “cash advance” guarantee a specific amount or a definite approval.
A realistic payday scenario
Imagine that my electricity payment is due on Friday, my salary arrives on Monday, and I am considering a short-term advance to cover the gap. I could use the app as an initial screening step: first, I would review what kind of advance is being discussed; next, I would write down the amount I actually need rather than choosing the largest figure shown; finally, I would compare the full repayment with the cost of waiting, negotiating a payment date, or using an existing overdraft facility.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
That last comparison is where many people could save themselves trouble. If a provider’s total repayment is higher than a small late-payment arrangement with the utility company, the advance may be the worse choice even if it is faster. I would also avoid borrowing extra simply because the application makes a larger amount appear available. A short-term product is easiest to manage when it solves one defined gap and has a repayment plan that fits the next income cycle.
For a user in that situation, the app’s convenience is real, but convenience can also hide the most important question: what will this cost from start to finish? I would keep a note of the amount requested, any stated fees or charges, the due date, and the final amount to repay before accepting anything. Taking a screenshot or saving the written terms for personal reference is a sensible habit, particularly when making a decision under time pressure.
What changed users may notice
The clearest version-related fact is that the app is currently at 1.1.3, following its release in late 2022. That gives existing users a concrete point of reference when checking whether they are running the latest build. It also helps explain why the app should be judged on the workflow available now, not on assumptions about future features or on the wording of an older installation.
I would not interpret a version number alone as proof of a major redesign, a new lending network, or improved approval odds. Those would be meaningful changes, but they should be visible in the actual experience and in the terms shown during use. From a reviewer’s perspective, the practical evolution to watch is whether the app makes the borrowing journey clearer: better explanations, easier access to repayment details, and fewer moments where a user has to guess what happens next.
For someone who already has the app installed, updating is worthwhile when an update is available through the normal app store process, but I would still reread the screens before submitting financial information. An update can change wording, navigation, or the way an offer is presented. Existing users should not assume that a familiar button means exactly the same thing after a product revision.
The app’s popularity provides some reassurance that many people have found it usable, but a high average rating is not a substitute for reading recent written feedback or checking the exact offer presented to me. Ratings often reflect ease of use, speed of the initial process, or general satisfaction, while the financial consequences depend on individual terms. I treat the rating as a reason to investigate, not as evidence that every borrowing experience will be identical.
Where it helps in everyday use
I think this app is most useful as a first-stop research tool for people who need to understand short-term cash options without beginning with a traditional credit-focused application. It may suit someone whose income is regular but whose timing is awkward, or someone who wants to see whether an advance route is available before spending time on a larger loan application.
Another useful workflow is to decide the repayment ceiling before opening the app. For example, I might determine that I can repay only a modest amount after my next paycheck, then reject any option that would leave too little for rent, food, transport, or other fixed commitments. This reverses the usual temptation to start with the amount offered and then work backward. The app becomes a tool for checking a decision I have already bounded, rather than a prompt to borrow more.
I would also use it alongside a simple written budget. The budget does not need to be complicated: list the next income, essential payments, the proposed repayment, and a small buffer for ordinary spending. If the repayment makes the following week impossible, the app has helped reveal that the advance is not affordable. That is a valuable result even when I decide not to proceed.
People who dislike visiting branches or filling out lengthy forms may appreciate a mobile-first starting point. The free download lowers the barrier to exploring the service, and the Everyone age classification makes the app broadly accessible from a store perspective. Still, accessibility should not be confused with suitability. A person can be old enough to use the app and still be in a situation where borrowing would deepen a financial problem.
The friction and risks I would take seriously
The biggest limitation is inherent in the product category: short-term cash can solve a timing problem while creating a repayment problem. If I repeatedly need an advance before each payday, the issue is no longer a one-off gap. In that case, I would stop using the app as a quick fix and look for a broader solution, such as adjusting recurring expenses, speaking with creditors, seeking free financial guidance, or building a small emergency reserve over time.
I would also be cautious about the phrase “no credit check.” It may describe how an application is assessed, but it does not tell me whether the product is affordable, whether other eligibility checks apply, or whether the provider will approve the request. It certainly does not eliminate the need to verify identity or provide financial details when required. I would read the complete terms and avoid treating a promotional label as a description of the entire agreement.
Privacy is another practical consideration. Any finance app may involve sensitive personal and financial information, so I would check the app’s current disclosures and make sure I understand who receives the information and why before submitting it. I would use a secure device, avoid public Wi-Fi for sensitive steps, and never share verification codes with another person. These habits matter more here than the convenience of completing a form quickly.
There is also a difference between an app being free and the financial service being free. The download may cost nothing, while an advance or loan can still carry fees, interest, or other charges. I would look for the total amount due, the repayment date, and the consequences of missing that date. If those details are difficult to find or are presented in a way I cannot understand, I would leave the process rather than rely on a vague promise of speed.
How it compares with familiar alternatives
Compared with a bank’s overdraft or an existing line of credit, this app may be more approachable for someone who does not want to begin with a conventional credit assessment. The bank alternative may nevertheless be cheaper or easier to manage for an established customer, particularly when the account already shows the available limit and repayment rules clearly. I would compare the total cost rather than choosing based only on which application feels faster.
Compared with borrowing from family or a trusted friend, the app offers a more formal route and avoids mixing money with a personal relationship. The personal option may be less expensive, but it can create emotional pressure or misunderstandings if the repayment date changes. If I chose that route, I would still put the amount and repayment plan in writing. The app is not automatically better; it is simply a different kind of arrangement.
Compared with a credit union, community lender, or employer-based advance, the app may be quicker to explore from a phone, while those alternatives may offer more personal guidance or a product designed around longer-term affordability. Someone with time to compare should not limit the search to one mobile application. A slower option can be the better option if it produces a manageable repayment and clearer support.
Compared with a budgeting app, Cash Advance - No credit Check serves a completely different purpose. A budgeting tool helps me prevent the next shortfall; this app is relevant after a shortfall is already pressing. I would use budgeting first whenever possible, because preventing a recurring gap is safer than repeatedly financing it. The two approaches can work together, but they should not be confused.
Who should try it, and who should skip it
I would recommend giving it a cautious look to a user who has a defined, temporary cash gap, understands that approval is not guaranteed, and is prepared to compare the complete repayment cost with other options. It is particularly reasonable as an information-gathering step when a traditional credit route is not the user’s preferred starting point.
I would tell someone to skip it if they are already using one advance to repay another, cannot identify where the repayment will come from, or are hoping the app will provide ongoing income. I would also skip it if the terms are unclear, if the requested permissions or information feel excessive, or if the person is under pressure to accept immediately. A financial decision that cannot survive a few minutes of careful reading is not one I would rush into.
Users who want detailed expense tracking, savings goals, investment tools, or a complete banking service should choose a different finance app. This product’s value comes from its focused cash-advance purpose, not from being an all-in-one money manager. Likewise, someone who can comfortably wait for payday may be better served by waiting and avoiding the cost of borrowing altogether.
What I would watch before relying on it
My main test would be clarity. I would watch whether the app explains the difference between checking options and receiving money, whether the full repayment is easy to locate, and whether the timing of a deposit is expressed plainly. These details matter more than a polished opening screen because they determine whether I can make an informed choice.
I would also watch how the current version develops. Future improvements would be meaningful if they make costs, eligibility, repayment schedules, and privacy choices easier to understand. I would not assume that a newer version automatically means better offers or lower prices. Those are separate questions that must be answered by the actual terms shown to each user.
Another point worth monitoring is how well the app serves returning users. A person who has used it once may need a clear record of what was requested, what was accepted, and when repayment is due. If the experience encourages repeated borrowing without helping users understand the pattern, that would be a serious weakness for a finance product. The best version of this kind of app should help users make a deliberate decision, not simply make borrowing feel effortless.
In the end, I see Cash Advance - No credit Check as a convenient way to explore a short-term cash option, not as free money and not as a substitute for financial planning. Its free access, broad Android compatibility, focused purpose, and strong user response make it worth investigating for the right situation. My recommendation is conditional: use it with a fixed amount in mind, compare the full repayment against alternatives, protect your personal information, and walk away if the terms do not make immediate sense. For a one-time timing problem, that approach may make the app useful; for a recurring shortage, a longer-term solution is the better choice.
Frequently Asked Questions
What is Cash Advance - No Credit Check, and how does it work?
Cash Advance - No Credit Check is a financial app designed to connect users with potential short-term loan or cash advance offers. After entering personal and financial information, the app may evaluate your request and show available options from third-party lenders. Approval, loan amounts, interest rates, fees, and repayment terms are not guaranteed and can vary depending on your location, income, credit profile, and lender requirements.
Can I really get a cash advance without a credit check?
The phrase “no credit check” should be understood carefully. Some providers may use alternative information instead of, or in addition to, a traditional credit report, while others may still perform a credit inquiry before making an offer. The app itself may not guarantee approval or eliminate credit checks entirely. Before accepting anything, review the lender’s disclosure documents and confirm whether the inquiry affects your credit score.
How much does borrowing through the app cost?
The total cost depends on the lender and the specific offer you receive. Possible charges may include interest, origination fees, service fees, late-payment penalties, expedited funding fees, or other costs. Short-term loans can have a high annual percentage rate even when the initial amount seems small. Carefully compare the APR, finance charge, repayment schedule, and total amount due before accepting an offer.
What information and permissions does the application request?
To match users with financial offers, the app or connected lenders may request details such as your name, address, employment information, income, bank account data, phone number, and Social Security or national identification information. Only provide sensitive data through official, secure channels. Check the privacy policy, app permissions, data-sharing practices, and lender identity, and avoid any service that asks for unnecessary access or an upfront payment.
What should I know about repayment and possible risks?
Cash advances are generally intended for short-term financial needs and must be repaid according to the lender’s schedule. Missing a payment may result in additional fees, collection activity, bank overdraft charges, or damage to your credit history if the account is reported. Make sure your next paycheck or income can cover the repayment, and consider safer alternatives such as a payment extension, employer advance, credit union loan, or assistance program.


